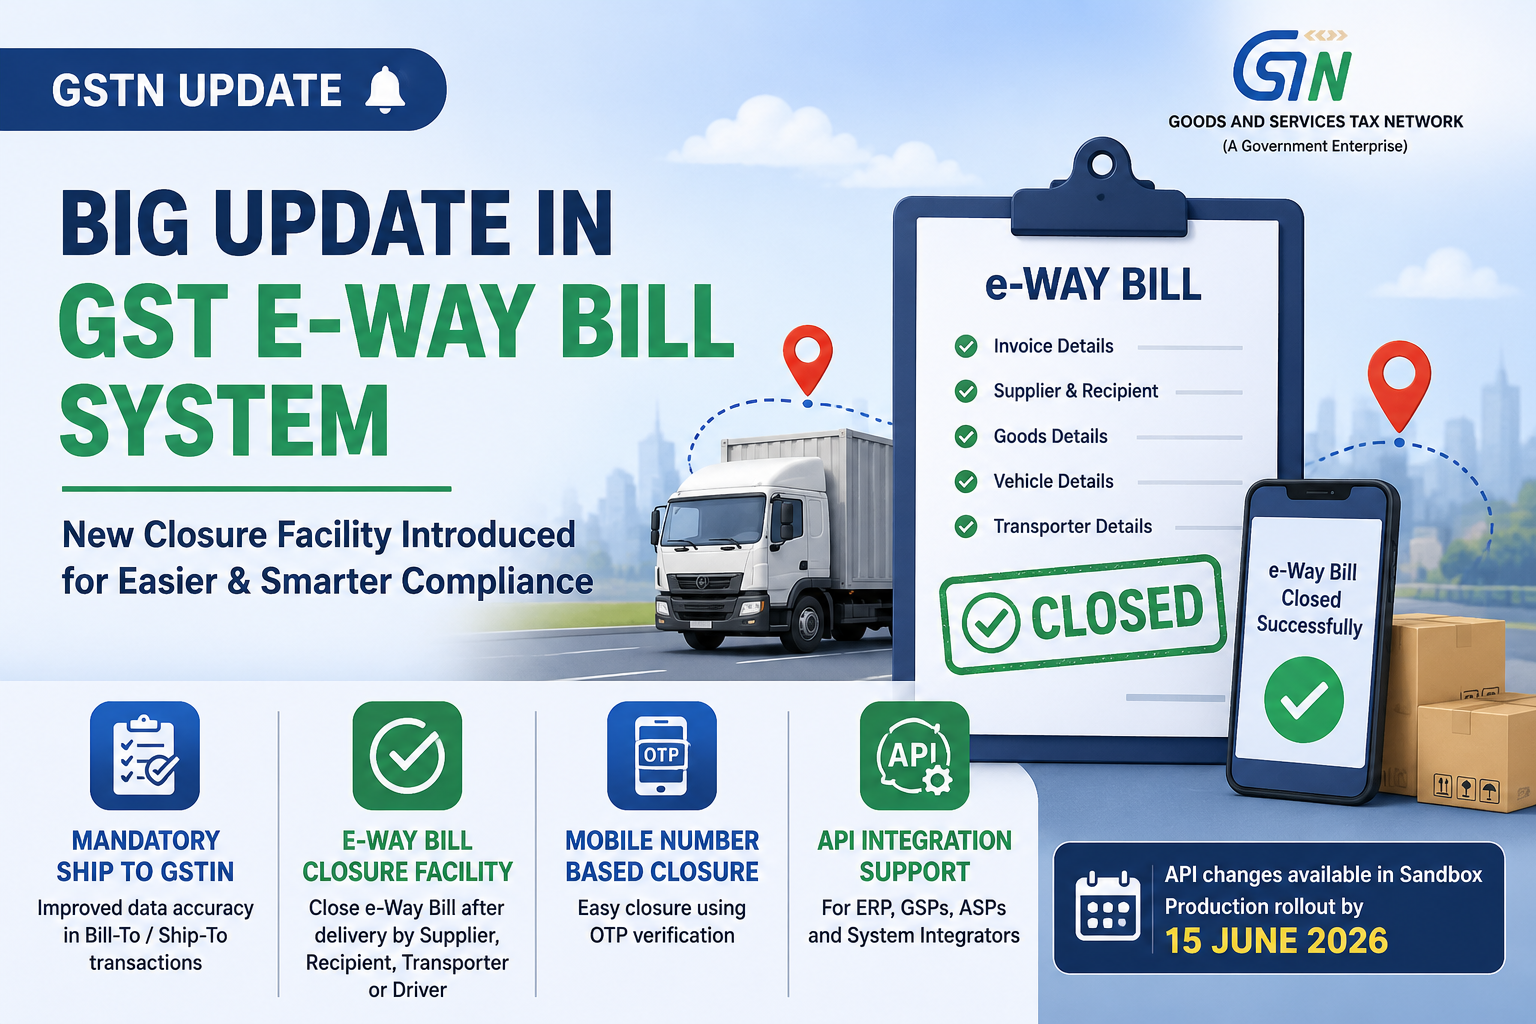
The GST Network (GSTN) has introduced important changes in the e-Way Bill (EWB) system. These changes are aimed at improving transparency, better tracking of goods movement, and reducing misuse of e-Way Bills.
The new system changes were announced through an official GSTN Advisory dated 20 May 2026.
Let us understand these updates in simple language.
What is an e-Way Bill?
An e-Way Bill is an electronic document required for movement of goods worth more than ₹50,000 under GST.
It contains details like:
- Supplier details
- Buyer details
- Goods details
- Vehicle details
- Transport information
It helps the government track movement of goods and prevent tax evasion.
Major Changes Introduced by GSTN
The latest advisory contains two major updates:
- Mandatory “Ship To GSTIN” in Bill-To / Ship-To cases
- Introduction of e-Way Bill Closure Facility
1. “Ship To GSTIN” Now Mandatory
What is a Bill-To / Ship-To Transaction?
Sometimes, goods are billed to one party but delivered to another location.
Example:
- ABC Ltd. in Delhi places an order.
- Goods are directly delivered to its branch in Jaipur.
In such cases:
- Bill To = Delhi office
- Ship To = Jaipur branch
Now, GSTN has made it mandatory to mention the “Ship To GSTIN” while generating the e-Way Bill.
What if the Consignee is Unregistered?
If the goods are being delivered to an unregistered person, then the value “URP” must be entered in the “Ship To GSTIN” field.
“URP” means:
Unregistered Person
This change will help improve tracking and reduce incorrect reporting.
2. New e-Way Bill Closure Facility Introduced
This is the biggest update.
Earlier, users could only CANCEL an e-Way Bill.
Now, GSTN has introduced a facility to CLOSE the e-Way Bill after successful delivery of goods.
Currently, this facility is voluntary.
Why Was This Facility Introduced?
Many times:
- Goods are delivered successfully,
- But the e-Way Bill remains active till expiry.
This creates issues like:
- Difficulty in tracking completed transactions
- Misuse risk
- Incorrect movement status
- Compliance confusion
The new closure facility helps mark the transaction as “completed”.
Who Can Close the e-Way Bill?
The following persons can close the e-Way Bill:
- Supplier
- Recipient
- Transporter
- Driver or authorized person
This gives flexibility to businesses and logistics operators.
How Can e-Way Bill Be Closed?
The closure can be done:
1. e-Way Bill-wise
You can close one specific e-Way Bill individually.
2. Date-wise
You can close multiple e-Way Bills generated on a particular date.
This is especially useful for businesses handling bulk deliveries daily.
Mobile Number-Based Closure Facility
A very useful feature has also been introduced.
At the time of generating the e-Way Bill, users can now provide a mobile number specifically for closure purposes.
That person can later close the e-Way Bill using OTP verification.
Where Can the Mobile Number Be Updated?
The mobile number can also be updated during:
- Vehicle update
- Consolidated e-Way Bill operations
- Validity extension
This provides operational flexibility.
Driver Can Also Close the e-Way Bill
This is a practical feature for transport businesses.
The driver or authorized person can:
- Open the e-Way Bill portal
- Enter the registered mobile number
- Verify through OTP
- Close the e-Way Bill
This is expected to reduce dependency on office staff.
Important Time Limit for Closure
The e-Way Bill can be closed:
- On the same day of delivery, or
- On the immediately next day
Businesses should ensure timely closure to maintain proper records.
API Facility Also Introduced
GSTN has also released API support for:
- ERP systems
- GSPs
- ASPs
- Large taxpayers
- System integrators
For API-based closure, the following details are required:
- e-Way Bill Number
- Closure Date
- Remarks
This will help large businesses automate the process.
Important Date for Implementation
GSTN has informed that:
- API changes are already available in Sandbox environment
- Production deployment is planned by 15 June 2026
Businesses using ERP or integrated software should immediately coordinate with their software vendors.
What Businesses Should Do Now
Recommended Action Steps
1. Update Internal SOPs
Businesses should update their internal logistics and GST procedures.
2. Train Staff
Accounts teams, dispatch teams, and transporters should be informed about the new closure process.
3. Update ERP Systems
ERP software should be modified to support:
- Mandatory Ship To GSTIN
- e-Way Bill closure
- Mobile-based closure
- API integration
4. Avoid Last-Minute Changes
Businesses should complete testing before the production rollout date.
Practical Benefits of This Update
The new system can provide several advantages:
Better Compliance
Completed deliveries can now be properly tracked.
Reduced Disputes
Closure confirms successful completion of transportation.
Better Audit Trail
Helps maintain proper movement records.
Operational Transparency
Transporters and businesses can monitor completed transactions more efficiently.
Important Point to Remember
Currently, the e-Way Bill Closure facility is VOLUNTARY.
It is not mandatory as of now.
However, businesses should start using it early because:
- It may become mandatory in future,
- Early adoption reduces compliance risk,
- Proper closure improves documentation quality.
Final Thoughts
The GSTN’s latest update is a significant step towards smarter and more transparent logistics compliance under GST.
The introduction of the e-Way Bill Closure facility will help businesses maintain cleaner records and improve transaction traceability.
Taxpayers, transporters, ERP vendors, and logistics operators should start preparing immediately before the production rollout scheduled for 15 June 2026.
Proper implementation at an early stage will help businesses avoid future compliance issues and ensure smoother GST operations.
Source:
GSTN Advisory dated 20.05.2026 regarding Enhancements in e-Way Bill Portal.